ebtEDGE NEW!

Screenshots
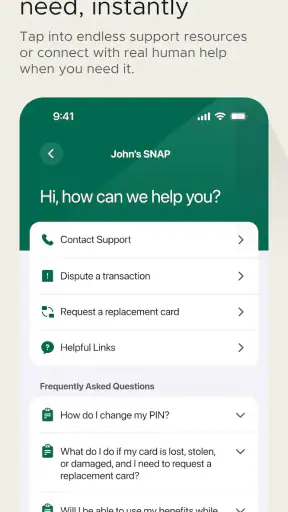
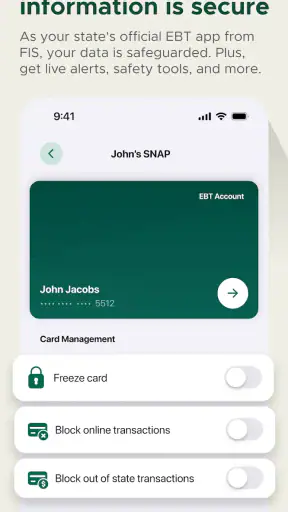
Details
- Rating
- 388.00 reviews
- Version
- 4.0.0
- Developer
- Fidelity Information Services LLC
Analysis by Norviv
Managing public benefits is rarely difficult because of one big task. It is difficult because several small questions arrive at inconvenient times: Is there enough available for a grocery trip? Did a recent purchase reduce the balance? Which account should be checked when SNAP, childcare, or WIC support is involved? ebtEDGE NEW! is built around making those checks easier from a phone, and that narrow purpose is also its main strength.
I reviewed it as a finance app rather than as a general budgeting tool. It is the official ebtEDGE app for SNAP, Childcare, and WIC benefits in participating states, developed by Fidelity Information Services LLC. It is free to use, rated for Everyone, and designed for devices running Android 7.0 or later. The current release is version 4.0.0, and its presence on the store is substantial, with over one hundred thousand installs.
My overall impression is practical rather than enthusiastic: this is the kind of app that can become genuinely useful when I need a quick benefit-account check, but it is not meant to replace a full personal-finance app, a state benefits portal, or direct help from an agency. Its value depends heavily on whether my state and benefit program are supported and whether I prefer checking information on a phone instead of using a card terminal, website, or telephone service.
One focused capability: checking benefit information when I need it
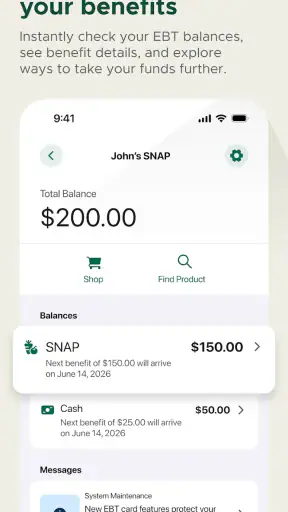
The most important capability here is simple access to benefit-account information. Instead of waiting until I am standing at a checkout or trying to remember what was left after the last shopping trip, I can use the app as a pocket reference for my SNAP, childcare, or WIC account. That changes the timing of the decision. I can check before leaving home, while planning a shopping list, or after a purchase when I want to understand the new balance.
That may sound modest, but timing matters with benefits. A balance check before shopping can prevent an awkward moment at the register. It can also help me separate what I can buy today from what should wait until the next benefit deposit. For a parent coordinating groceries and childcare expenses, having the relevant account information in one place is more useful than opening a general banking app that cannot interpret benefit activity.
I also like that the app is aimed at several benefit programs rather than only one narrow use. SNAP users may approach it mainly as a food-benefit balance tool, while WIC users may need a more careful view of what remains available for eligible purchases. Someone connected with childcare benefits may have a different reason for opening it altogether. The same app can therefore fit different household routines, even though the underlying need is similar: see the account information before making a decision.
The app’s average rating is 3.2 from around six hundred ratings, with nearly four hundred written reviews. I read that as a useful warning about expectations. The concept is valuable, but convenience apps tied to government benefit systems can feel frustrating when account access, state support, or transaction information does not behave as smoothly as a modern banking app. I would install it for the direct access it offers, not because I expect a polished financial dashboard.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Why this is different from a normal banking app
A regular bank app is designed around checking accounts, transfers, card spending, and sometimes budgeting. That is not the job of ebtEDGE. Its role is closer to a benefits-account window. The distinction matters because I should not expect it to categorize my household spending, show every bank account, or help me build a monthly budget.
Compared with checking a paper notice or relying on memory, the app can be more immediate. Compared with calling a benefits service, it can be more convenient for a quick lookup. Compared with a state website, a phone app may be easier when I am already away from a computer. The trade-off is that an app does not automatically solve every account problem. If the issue involves eligibility, a missing deposit, a replacement card, or a case decision, I may still need the appropriate official support channel.
This is the first non-obvious point I would keep in mind: the app is most valuable as a decision-before-action tool. It is not necessarily where I resolve complicated benefit questions. Its practical effect is strongest when a small piece of current account information helps me decide whether to shop, what to plan, or whether to investigate an unexpected change.
How the experience works in everyday use
My recommended routine is to treat the app like a short check-in rather than something that stays open all day. I would open it before making a shopping list, review the relevant benefit account, and then close it. After using benefits, I would check again if I needed to confirm the effect of the transaction. This keeps the app focused and reduces the temptation to treat it like a complete money-management service.
The first important step is choosing the correct benefit context. A household that uses more than one supported program should slow down here instead of assuming that every balance belongs to the same account. SNAP and WIC serve different purposes, and childcare benefits are not interchangeable with food benefits. A quick glance at the wrong account could create a misleading sense of available funds.
That leads to a practical habit: before relying on a displayed figure, I would confirm which program I am viewing and whether the information matches the account I intend to use. This is especially important for households where one adult manages several cards or where benefits are used for different family members. The app can centralize access, but centralization also makes careful labeling and attention more important.
I would also avoid using a single balance check as a substitute for planning. For SNAP or WIC shopping, the amount available is only one part of the decision. Eligible items, store procedures, and the way a purchase is processed still matter. The app helps answer “how much appears to be available?” It does not turn every product in a cart into an eligible purchase, and it should not be treated as a guarantee that a complicated transaction will proceed exactly as expected.
A second useful insight is to check after an unusual transaction, not only after an ordinary grocery trip. If a purchase was split between benefits and another payment method, or if I used more than one benefit category, reviewing the account afterward can help me notice whether the result looks as expected. That does not replace an official dispute process, but it gives me a clearer starting point if something needs attention.
A realistic shopping-day example
Imagine I am planning a grocery trip for the evening and have a limited amount of time. I open the app before leaving, select the benefit account I intend to use, and check the current information. I then adjust my list rather than discovering at checkout that my original plan was too expensive. If I use a combination of eligible and non-eligible items, I can later open the app again to review the account information and compare it with the receipt.
The benefit is not dramatic automation. It is reduced uncertainty at two specific moments: before shopping and after spending. That is why I would recommend it to someone who often makes last-minute grocery decisions or manages benefits for a household. A person who rarely needs to check an account may not notice much value, but frequent users can save repeated calls, website visits, or guesswork.
For WIC users, I would be even more deliberate. WIC shopping can involve category-specific choices, so I would use the app as one part of the process rather than the entire process. I would still pay attention to the approved items and the store’s checkout flow. The app can help me understand the account side of the trip, while the receipt and program guidance help me understand the purchase side.
For someone connected with childcare benefits, the best routine may be different. Instead of checking before a grocery trip, the app may be more useful during periodic account reviews or when confirming that the account information is current before relying on it. The important point is that the same tool supports different schedules; I should not assume that every user needs to open it daily.
Questions I would settle before depending on it
The first question is whether my state and benefit program are supported. The app is described as official for SNAP, Childcare, and WIC benefits in your state, but “your state” is the practical detail that determines whether it will help me. I would verify support through the relevant official route before making it my only way to check an account.
The second question is whether it shows the kind of information I actually need. If my goal is a quick balance or account review, it may fit. If I need to change a case, understand eligibility, upload documentation, or resolve a disputed transaction, I would not assume the app is the right destination. Those are different tasks from viewing benefit information.
The third question is what I should do if the app and my receipt appear inconsistent. My approach would be to keep the receipt, note the date and transaction details, and use the official support process associated with the benefit program. I would not repeatedly refresh the app and assume that a delayed or confusing display is proof that the transaction was reversed or duplicated.
The fourth question is whether an older phone can run it. The minimum requirement is Android 7.0, which makes the app accessible to many older devices. Still, the operating system requirement is only the starting point. I would keep the phone’s software and app version current where possible, especially for an app that handles account access.
Finally, I would ask whether a free app is worth installing when I can use other options. For me, the answer is yes if I check benefits regularly and want a phone-based shortcut. If I only need occasional information and already have a reliable official website or telephone process, adding another login may not improve my routine.
Where it helps most, and where the trade-offs appear
The strongest scenario is a household that needs frequent, quick visibility into benefit accounts but does not want to use a desktop browser every time. A parent shopping with a strict budget, a caregiver managing more than one benefit program, or someone who wants to review an account after a purchase can all gain from having the information available on a phone.
Another strong scenario is preparation before leaving home. I would rather make a realistic shopping list in my kitchen than revise it beside a checkout line. The app supports that change by moving the balance check earlier in the process. It is a small workflow improvement, but it can reduce stress when every item matters.
The main trade-off is scope. ebtEDGE is not a universal finance companion. It does not belong in the same mental category as an app that tracks bank accounts, bills, credit cards, savings goals, and spending trends. If I want a complete household budget, I need a separate tool. Using this app for that purpose would leave me with an incomplete picture of my finances.
A second trade-off is dependence on the benefit system behind the app. The app can present account information, but it cannot make a state process faster or clarify a policy question by itself. If my problem is administrative rather than informational, I may still need a caseworker, agency website, phone line, or other official channel. That is not a reason to dismiss the app; it is a reason to use it for the job it is best suited to do.
A third trade-off is that convenience can encourage overconfidence. Seeing an available amount on a screen may make me feel ready to shop, but it does not remove the need to check product eligibility, understand the separate benefit categories, or keep receipts. My advice is to use the app as a reliable checkpoint, not as permission to stop paying attention.
There is also a human-factor issue. People who are comfortable with phone apps may find a quick account check easier than a call. Someone who shares a phone, changes devices often, or dislikes managing another account login may prefer a different method. In that case, the app’s central advantage—immediate access from a personal device—may not feel like an advantage at all.
For security, I would treat the phone as an account-access device rather than a casual browsing device. I would use a screen lock, avoid sharing login details, and sign out or protect access if other people regularly use the phone. These are sensible habits for any finance-related app, but they matter especially when the account is connected to essential household benefits.
One more practical trade-off is the difference between “available information” and “actionable resolution.” The app may help me notice that something changed, but noticing is not the same as fixing it. If a balance looks wrong, the best next step is organized follow-up: save the receipt, record the relevant details, and contact the proper benefits service. The app is useful evidence for my own review, but I would not treat it as a complete customer-service desk.
Who gains the most from installing it
I think the best match is someone who uses SNAP, WIC, or childcare benefits and regularly wants a fast account check while away from a computer. The app is especially sensible for people who plan shopping around a limited balance, manage benefits for a family, or want to review account information after a transaction.
It can also help a person who has previously relied on memory. Replacing “I think there should be enough left” with a deliberate check before shopping is a meaningful improvement, even if the app does nothing else. That simple habit can make the benefit account feel more manageable.
I would be more cautious about recommending it as the only option for someone dealing with an active eligibility dispute, a complicated case change, or a transaction problem that requires official investigation. In those situations, the app may still be useful for checking information, but another official channel is likely more appropriate for resolution.
I would also suggest skipping it if the person does not use one of the supported benefit programs or already has a dependable method that is faster for their circumstances. A free download is not automatically worthwhile if it adds another account to maintain without solving a real problem.
For most eligible users, the decision comes down to frequency. If I check benefits several times during a typical month, a dedicated app earns its place on my phone. If I check only rarely, the usual website or telephone route may be enough. The app’s value grows through repeated small conveniences rather than one impressive feature.
My final view after using it as a benefits tool
ebtEDGE NEW! succeeds when I judge it by its focused purpose: giving SNAP, childcare, and WIC users a convenient way to review benefit-account information from a phone. I would use it before shopping, after an unusual purchase, and whenever I needed to replace guesswork with a current account check.
Its limitations are just as important. It is not a budgeting suite, not a general bank replacement, and not a complete solution for administrative or transaction disputes. The moderate 3.2 average rating suggests that the experience may not feel effortless for everyone, so I would keep an alternative official contact method available rather than depending on the app alone.
Still, I see a clear everyday benefit for the right person. When a quick check helps me adjust a grocery list, understand what remains, or prepare better for a benefit-related purchase, the app earns its place. I recommend it to eligible users who want that specific convenience, with one condition: use it as a focused account-checking companion, and keep receipts and official support channels in the routine for everything more complicated.
Frequently Asked Questions
01What is ebtEDGE NEW! and what can I use it for?
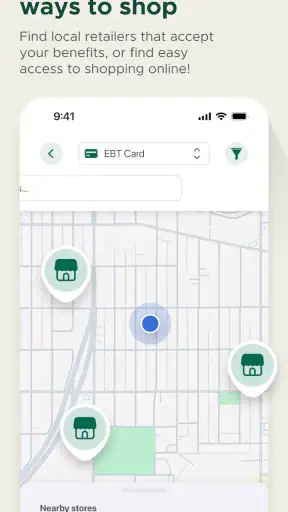
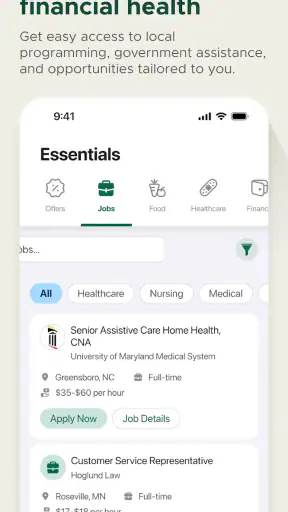
ebtEDGE NEW! is a mobile service designed for people who use eligible Electronic Benefit Transfer (EBT) programs. After signing in, users can typically review available food or cash benefit balances, check recent transactions, view important account details, and locate participating retailers or resources. The exact features and supported programs may vary depending on your state or benefit provider, so availability should be confirmed during setup.
02How do I sign in to ebtEDGE NEW!?
To use ebtEDGE NEW!, you generally need an active EBT account, card information, and the login details required by your state’s EBT system. New users may need to register before accessing account information, while existing users can sign in with their established credentials. Make sure the app is downloaded from an official store and avoid sharing your PIN, password, or security codes with anyone.
03Can ebtEDGE NEW! show my current EBT balance and transaction history?
Yes, one of the main reasons to use ebtEDGE NEW! is to check benefit information without calling customer service or visiting a participating location. Depending on your state’s implementation, the app may display your current balance, recent purchases, deposits, withdrawals, and other account activity. Balance updates can sometimes be delayed, so the amount shown may not always reflect a transaction completed moments earlier.
04Is ebtEDGE NEW! available in every state and for every EBT card?
Support for ebtEDGE NEW! depends on the state agency, benefit program, and EBT card provider connected to your account. Some users may have access to the full range of features, while others may see a more limited selection or be directed to a different official service. If your card is not recognized, check your state’s benefits website or contact the number printed on the back of your EBT card.
05Is ebtEDGE NEW! safe to use, and what should I do if my card is lost?
The app is intended to provide secure access to EBT account information, but users should still follow basic security practices. Use a private device, keep the app updated, enable available security protections, and never disclose your PIN or login credentials. If your card is lost, stolen, or used without permission, report it immediately through the official support number or agency listed on your card.


